


Crypto Tax Reconciliation for Exchanges Where Data Is Not Available: A Complete Guide
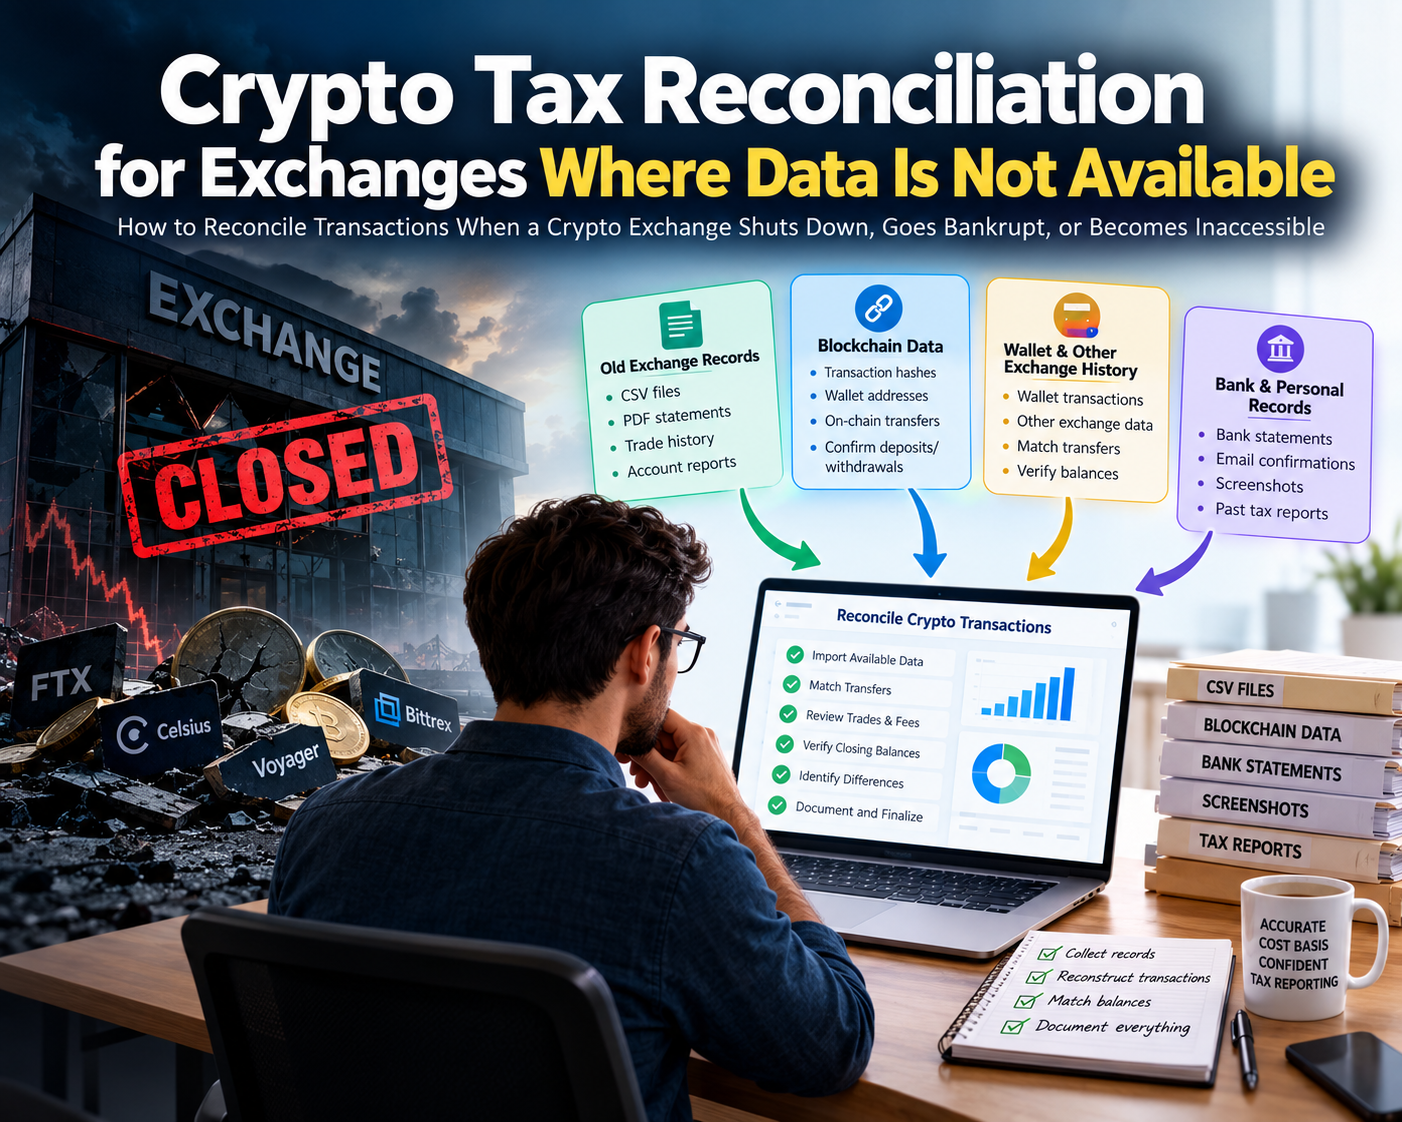
Crypto Tax Reconciliation for Exchanges Where Data Is Not Available: A Complete Guide
TL;DR: When a crypto exchange shuts down, goes bankrupt, or becomes inaccessible, you may no longer be able to download your transaction history or connect the account to crypto tax software. You can still reconstruct and reconcile the transactions using old exchange records, blockchain data, wallet histories, bank statements, and other supporting evidence, but missing crypto should not automatically be recorded as a tax loss.
What Happens to Your Crypto Tax Records When an Exchange Shuts Down?
Crypto investors often rely on exchanges to maintain their transaction history. Normally, you can connect an exchange to crypto tax software through an API, upload a CSV file, or download account statements.
The situation becomes much more complicated when the exchange:
- Shuts down permanently
- Files for bankruptcy
- Stops providing customer access
- Discontinues its API
- Removes historical transaction downloads
- Freezes customer accounts
- Enters liquidation or restructuring
- Becomes inaccessible because the company or platform no longer operates
Examples of exchanges and crypto platforms that have faced shutdowns, bankruptcy, insolvency, or major operational disruptions include Celsius, FTX, Voyager, Bittrex, BitSeven, etc.
When this happens, the challenge is not simply figuring out what happened to the crypto. You also need to reconstruct the tax history of the assets that moved through the exchange.
That history can affect:
- Cost basis
- Capital gains and losses
- Holding periods
- Transfers between wallets
- Trading activity
- Transaction fees
- Staking or other income
- Assets remaining on the failed exchange
- Later bankruptcy distributions or recoveries
This is where crypto tax reconciliation becomes particularly important.
Why Exchange Shutdowns Make Crypto Tax Reconciliation Difficult
A normal reconciliation process might look like this:
Exchange API/CSV → Crypto tax software → Match transfers → Reconcile balances → Calculate gains/losses
A failed exchange can break that process at the first step.
You may have no working API, no CSV download, and no customer account access.
Even if you remember approximately how much crypto you held, that is generally not enough to reconstruct the complete transaction history.
For example, imagine an investor purchased Bitcoin on an exchange in 2021, traded it several times in 2022, withdrew part of it to a personal wallet, and left the remaining Bitcoin on the exchange.
The exchange then shuts down.
To calculate the correct tax position, you may need to establish:
- When the Bitcoin was acquired
- How much was acquired
- The acquisition cost
- Which portions were sold or traded
- Which portions were transferred elsewhere
- How much was paid in fees
- What remained on the exchange
- Whether the remaining assets were later recovered
- Whether the investor received a bankruptcy distribution
- How that recovery should be treated under the applicable tax rules
That is much more than simply importing a CSV.
Step 1: Identify the Exchange's Current Status
Before attempting reconciliation, determine exactly what happened to the exchange.
This is an important first step because the available records and the appropriate reconstruction process can depend on the exchange's current status.
Determine whether the exchange:
- Is still operating
- Has stopped accepting new customers
- Has suspended withdrawals
- Has disabled its API
- Has stopped providing transaction downloads
- Has entered bankruptcy proceedings
- Has entered liquidation
- Has been acquired
- Has transferred customer accounts to another platform
- Has established a claims or recovery portal
Also determine whether customers still have access to their historical account information.
Why this matters
A company that has stopped normal operations may still maintain historical records.
For example, a bankrupt exchange may establish a dedicated claims or customer portal where users can access account information or submit claims.
Therefore, "the exchange shut down" does not necessarily mean "all transaction records are gone."
Step 2: Try to Access the Exchange Account
The first practical step is simple: try logging into the exchange account.
If the account is still accessible, look for Transaction histories, trade records or account statements and download everything that is available.
Do not download only the files you think you need.
A seemingly irrelevant file can become important later when investigating a missing transaction, unexplained balance, or cost-basis discrepancy.
Contact the exchange or claims administrator
If the normal account login no longer works, check whether the exchange has:
- A bankruptcy claims portal
- A customer information portal
- A records-request process
- A support email
- A court-appointed administrator or claims agent
- A successor company handling customer records
For example, FTX customers have had access to transaction-history information through the FTX Claims Portal.
For Celsius exchange transactions export, you can follow the steps mentioned in the link below:
If an exchange provides an official method for retrieving historical records, use that source before relying on estimates or reconstructed data.
Step 3: Search for Your Own Historical Crypto Records
If you cannot access the exchange, the next source of information is your own records.
Many crypto investors have transaction data stored somewhere without realizing how valuable it is.
Search for:
- Old CSV files
- Excel spreadsheets
- PDF account statements
- Crypto tax platform previously used
- Downloaded exchange reports
- Screenshots
- Email confirmations including Trade, Deposit or Withdrawal confirmations
- Bank/Credit card statements
Also search old email accounts for the exchange name.
Useful search terms can include:
- Exchange name
- "Deposit"
- "Withdrawal"
- "Trade"
- "Transaction"
- "Statement"
- "CSV"
- "BTC"
- "ETH"
- "USDT"
- "Account history"
Old tax reports can be particularly useful
Suppose an investor used a crypto tax platform in 2022 and generated a tax report before the exchange disappeared.
That report may contain valuable information about:
- Historical transactions
- Cost basis
- Acquisition dates
- Disposals
- Transfers
- Gains and losses
Even if the original exchange CSV is no longer available, an old tax report can provide evidence for reconstructing the account.
However, an old tax report should not automatically be treated as perfect. It should still be reviewed against other available records.
Step 4: Check Other Exchanges and Wallets
One of the most useful sources of information is often the other side of the transaction.
Consider this example:
An investor cannot access their Celsius account.
However, their personal Ethereum wallet shows:
2 ETH → Celsius deposit address
That blockchain transaction can provide evidence that 2 ETH was transferred to Celsius.
Similarly, suppose an investor withdrew 5 BTC from a failed exchange to a personal wallet.
The wallet's blockchain history may show the exact incoming transaction.
This can help establish that the transaction was a transfer, rather than a sale.
Look for both sides of every transfer
For every transaction you reconstruct, try to identify:
Sending account → Transaction → Receiving account
For example:
Coinbase → Personal Wallet
or
Personal Wallet → Celsius
or
FTX → Personal Wallet
or
Exchange A → Exchange B
This is important because crypto tax software can sometimes incorrectly classify a transaction as a taxable disposal when it is actually a transfer between accounts owned by the same taxpayer.
Step 5: Use Blockchain Data When Exchange Data Is Missing
Blockchain data can be extremely valuable when exchange records are unavailable.
For blockchain-based assets, you may be able to use:
- Transaction hashes
- Wallet addresses
- Block explorers
- On-chain timestamps
- Token amounts
- Receiving addresses
- Sending addresses
- Smart-contract interactions
For example, suppose the exchange CSV is unavailable but the investor's wallet shows:
Wallet A → Exchange Deposit Address: 2.00 ETH
The blockchain record can help establish that 2 ETH was sent to the exchange.
The transaction can then be manually reconstructed in the crypto tax software if necessary.
Important limitation
Blockchain data does not necessarily tell you everything about the tax nature of a transaction.
A blockchain transaction can show that an asset moved, but it may not tell you:
- Why it moved
- Who controlled the receiving address
- Whether it represented a sale
- Whether it was a loan
- Whether it was a gift
- Whether it was a transfer between accounts owned by the same taxpayer
- What fiat value should be assigned for tax purposes
Therefore, blockchain data should be combined with other evidence rather than treated as a complete substitute for exchange records.
Step 6: Reconstruct Deposits and Withdrawals
Once you have collected the available evidence, begin reconstructing the exchange account.
Start with deposits and withdrawals.
For each transaction, document:
| Date | Asset | Amount | From | To | Transaction Type | Evidence |
| Jan. 10 | BTC | 5.00 | Personal Wallet | Exchange | Deposit | Blockchain |
| Mar. 15 | BTC | 1.00 | Exchange | Personal Wallet | Withdrawal | Blockchain |
| Apr. 20 | ETH | 2.00 | Personal Wallet | Exchange | Deposit | Wallet history |
Do not simply enter numbers until the software produces the balance you expect.
Every material adjustment should have a reasonable explanation and supporting evidence.
Step 7: Reconstruct Trading Activity
After deposits and withdrawals, review the trading activity.
If historical trade records are available, import them into your crypto tax software.
If they are not available, look for alternative evidence such as:
- Previous exchange exports
- Tax reports
- Account statements
- Trade confirmations
- Screenshots
- Emails
- Records from another connected tax platform
You may need to manually reconstruct some transactions.
For each trade, determine as accurately as possible:
- Date
- Asset sold
- Quantity sold
- Asset received
- Quantity received
- Transaction value
- Trading fee
- Relevant transaction ID, if available
The goal is to reconstruct the economic transaction, not simply force the software balance to match a desired number.
Step 8: Reconcile Exchange Fees
Fees are easy to overlook when reconstructing historical crypto activity.
Depending on how the exchange charged fees, they may appear as:
- Separate cryptocurrency transactions
- Deducted amounts from the asset sold
- Additional amounts deducted from the asset received
- Fiat charges
- Trading fees
- Withdrawal fees
For example, an investor might believe they purchased exactly:
1.000 BTC
But the actual transaction could have involved a trading fee that affects the quantity received or the transaction's tax basis.
Historical records should therefore be reviewed carefully before assuming that the visible trade amount represents the complete transaction.
Step 9: Determine the Crypto Balance at the Time of Shutdown
One of the most important questions is:
How much cryptocurrency was actually left on the exchange when it became inaccessible?
Try to obtain evidence of the closing balance from:
- Exchange statements
- Account screenshots
- Bankruptcy claims
- Customer account records
- Historical tax software
- Downloaded CSV files
- Emails
- Court or claims documents
- Other reliable records
For example, suppose the reconstructed account shows:
- 7.9 BTC
- 30 ETH
- 5,100 USDT
remaining immediately before the exchange became inaccessible.
Those balances should be compared against whatever evidence is available.
Step 10: Match the Closing Balance in Your Crypto Tax Software
After reconstructing the transactions, compare the calculated closing balance with the documented exchange balance.
Suppose the documentation indicates:
2.90 BTC remaining
but your reconciliation software calculates:
3.15 BTC
There is a 0.25 BTC difference.
Do not simply delete 0.25 BTC to make the numbers match.
Investigate the difference.
Potential causes include:
- Missing withdrawals
- Missing deposits
- Duplicate transactions
- Incorrect transfer matching
- Incorrect fees
- Missing trades
- Incorrect transaction dates
- Wrong quantities
- Incorrect classifications
- Unsupported manual adjustments
- Transactions imported from multiple sources
- Internal transfers incorrectly treated as taxable events
This investigation is the core of the reconciliation process.
Example: Reconstructing a Closed Exchange Account
Suppose an investor used Exchange ABC.
The available records show:
- 5 BTC deposited
- 1 BTC sold for USDT
- 1 BTC withdrawn to the investor's personal wallet
- 0.1 BTC paid in fees
- 2.9 BTC remained on the exchange
The balance calculation would be:
5 BTC deposited
− 1 BTC disposed of through trading
− 1 BTC transferred to another wallet
− 0.1 BTC fees
= 2.9 BTC remaining
The software should ultimately reflect the same closing position, assuming these records are complete and correctly classified.
If the software instead shows 2.6 BTC, the difference needs to be investigated.
The objective is not to create a manual adjustment of 0.3 BTC simply because that is what is needed to make the balance match.
The objective is to find why the 0.3 BTC is missing.
Do Not Automatically Classify Missing Crypto as a Tax Loss
This is one of the most important issues when dealing with a bankrupt or failed crypto exchange.
If an exchange becomes inaccessible and the investor cannot withdraw their cryptocurrency, it does not automatically mean that the cryptocurrency should be recorded as a capital loss.
There may still be:
- A legal claim against the exchange
- A bankruptcy claim
- A pending distribution
- A partial recovery
- A future recovery
- A settlement
- Another form of compensation
The tax treatment can depend on the relevant jurisdiction and the specific facts.
Therefore, a crypto tax reconciliation should first establish what happened to the asset before deciding how the event should be treated for tax purposes.
Reconciliation and tax treatment are separate questions
This distinction is important.
Question 1: What happened to the crypto?
This is a reconciliation question.
Question 2: How should the event be treated for tax purposes?
This is a tax question.
The first question should be answered as accurately as possible before attempting to answer the second.
A crypto accountant or crypto tax advisor can help analyze the tax consequences based on the applicable jurisdiction and the taxpayer's circumstances.
What Happens When the Investor Receives a Bankruptcy Distribution?
A failed exchange may eventually distribute some assets or cash to creditors or customers.
For example:
2022: Investor deposits 3 BTC on Exchange ABC
2023: Exchange becomes insolvent
2024: Investor files a claim
2026: Investor receives a distribution
The distribution should not simply be ignored because the original exchange transaction occurred several years earlier.
The reconciliation should preserve the history of:
- The original acquisition
- The transfer to the exchange
- The exchange's closing balance
- The investor's claim or recovery
- Any cryptocurrency or cash ultimately received
The precise tax treatment of the recovery depends on the applicable tax rules and facts.
This is why it is important to retain the original reconciliation and supporting documentation even after receiving a distribution.
Consider the Impact Across Multiple Tax Years
A failed exchange can affect several tax years.
For example:
- 2021: Crypto purchased
- 2022: Crypto transferred to the exchange
- 2023: Crypto traded on the exchange
- 2024: Exchange becomes inaccessible
- 2025: Bankruptcy claim established
- 2026: Distribution received
Looking only at the year in which the exchange failed may produce an incomplete tax history.
Earlier transactions can affect:
- Cost basis
- Acquisition dates
- Holding periods
- Capital gains
- Capital losses
- Remaining asset balances
This is particularly important when an investor has used the exchange for several years.
What If Only Partial Exchange Data Is Available?
Partial data is common.
For example, you might have:
- 2019–2021 transaction history
- No records for 2022
- A 2023 account statement
- Blockchain records for withdrawals
- Bank statements showing fiat deposits
- A bankruptcy claim showing the final balance
You do not necessarily need to abandon the reconciliation.
Instead, identify which portions are supported by direct records and which portions need reconstruction.
Create an evidence hierarchy
A practical approach is to prioritize:
- Original exchange transaction records
- Official account statements
- Blockchain transaction data
- Wallet records
- Bank and credit card records
- Previously generated tax reports
- Email confirmations
- Screenshots
- Other contemporaneous documentation
- Reasonable reconstruction based on multiple supporting records
The weaker the evidence, the more carefully the adjustment should be documented.
How a Crypto Accountant Can Help
A closed-exchange reconciliation can become extremely time-consuming when multiple years, wallets, and exchanges are involved.
A crypto accountant can help reconstruct the transaction history and identify inconsistencies that may not be obvious to an investor.
The process may involve:
- Reviewing historical exchange records
- Importing available CSV files
- Reviewing wallet addresses
- Checking blockchain transactions
- Matching deposits and withdrawals
- Identifying duplicate transactions
- Reconstructing missing transfers
- Reviewing transaction classifications
- Investigating negative balances
- Reconstructing cost basis
- Comparing calculated and documented balances
- Creating an audit trail
For particularly complex cases, a crypto tax advisor may also need to review the tax treatment of the resulting transactions.
Common Mistakes When Reconciling a Failed Exchange
1. Treating all missing crypto as a loss
An inaccessible balance is not automatically a deductible tax loss.
First determine what happened to the asset and whether the investor has a claim or potential recovery.
2. Using only the final balance
A final balance tells you how much crypto remained, but not necessarily how that crypto was acquired.
Cost basis often depends on transactions that occurred years earlier.
3. Ignoring blockchain data
When exchange records disappear, blockchain records can provide important evidence about deposits and withdrawals.
4. Treating every exchange deposit as a purchase
A deposit may simply be a transfer from another wallet.
Incorrectly classifying transfers can create artificial taxable gains or losses.
5. Creating arbitrary manual adjustments
If the software does not balance, investigate the difference before making an adjustment.
6. Ignoring transaction fees
Fees can affect quantities and tax calculations and should be included where appropriate.
7. Reconciling only the current tax year
Historical transactions may affect the current year's cost basis and gains/losses.
8. Failing to document assumptions
If a transaction had to be reconstructed, record:
- What was reconstructed
- Why it was reconstructed
- What evidence was used
- What assumptions were made
- Who reviewed the adjustment
Good documentation can be extremely valuable later.
A Practical Workflow for Closed-Exchange Crypto Tax Reconciliation
A structured process can make a difficult reconciliation much easier.
Phase 1: Investigate
- Identify the exchange's current status.
- Determine whether the exchange still provides account access.
- Check for bankruptcy or claims portals.
- Check whether historical data can be downloaded.
Phase 2: Collect records
- Download all available exchange records.
- Search old computers and cloud storage.
- Search email accounts.
- Collect bank and credit card statements.
- Gather old crypto tax reports.
- Identify all relevant wallets.
Phase 3: Reconstruct
- Import available exchange data into your crypto tax software.
- Import wallet transactions.
- Reconstruct missing deposits.
- Reconstruct missing withdrawals.
- Reconstruct trades where sufficient evidence exists.
- Add appropriate fees.
- Match internal transfers.
Phase 4: Reconcile
- Calculate the exchange's closing balance.
- Compare it with documented balances.
- Investigate discrepancies.
- Identify duplicate or missing transactions.
- Review negative balances and unexplained quantities.
- Confirm the final position.
Phase 5: Review the tax consequences
- Identify taxable disposals.
- Review cost basis.
- Review holding periods.
- Separately analyze inaccessible assets or claims.
- Review later recoveries or bankruptcy distributions.
- Apply the tax rules applicable to the investor's jurisdiction.
Phase 6: Document
- Save the supporting records.
- Document manual adjustments.
- Document assumptions.
- Retain reconciliation workpapers.
- Preserve the final transaction database and tax reports.
Build an Audit Trail for Every Manual Adjustment
When exchange data is unavailable, documentation becomes even more important.
For every material manual adjustment, consider recording:
Item | Example |
Transaction date | March 15, 2022 |
Asset | ETH |
Quantity | 2.00 ETH |
Transaction type | Transfer |
Source | Blockchain transaction |
Transaction hash | Available |
Receiving address | Exchange deposit address |
Reason for adjustment | Exchange CSV unavailable |
Supporting document | Blockchain record |
Reviewer | Crypto accountant |
This creates a clear trail showing how the transaction was reconstructed.
The goal is that another person should be able to look at the work later and understand why the transaction was entered that way.
What If There Is Absolutely No Exchange Data?
Sometimes the records are genuinely incomplete.
In that situation, do not invent transactions simply to make the account balance.
Instead, use all available evidence to establish the most supportable transaction history.
For example, if you know:
- 5 BTC was transferred into the exchange
- 2 BTC was later withdrawn
- 3 BTC remained when the exchange became inaccessible
but you do not have records showing what happened inside the exchange, you may need additional evidence before reconstructing trading activity.
Potential sources include:
- Other tax software
- Historical statements
- Blockchain records
- Bank records
- Email confirmations
- Exchange claim documents
- Screenshots
- Counterparty records
If the evidence is insufficient to establish a particular transaction, that limitation should be documented rather than hidden.
The Difference Between Reconciliation and Tax Filing
It is useful to separate these two processes.
Crypto reconciliation
The purpose of reconciliation is to determine:
- What transactions occurred?
- What assets were acquired?
- What assets were disposed of?
- What was transferred?
- What fees were charged?
- What balances remained?
- What is the correct cost basis?
The purpose of tax filing is to determine how those transactions should be reported under the applicable tax laws.
The two processes are connected, but they are not identical.
A properly reconciled account gives the taxpayer and their crypto tax advisor a much stronger foundation for preparing the applicable tax reports.
Frequently Asked Questions
Can I reconcile a crypto exchange that has completely shut down?
Yes. A closed exchange can often still be reconciled using historical CSV files, account statements, blockchain records, wallet data, bank statements, old tax reports, screenshots, and other evidence.
The difficulty depends on how much reliable historical information remains available.
What if I cannot log into my old exchange account?
Start by searching for historical records that you previously downloaded.
Then check whether the exchange has a bankruptcy, claims, or customer-information portal. Blockchain records and records from other exchanges can also help reconstruct transfers.
Can blockchain data replace an exchange CSV?
Not completely.
Blockchain data can provide strong evidence for on-chain transfers, but it may not contain information about internal exchange trades, fees, conversions, or other off-chain activity.
It is best used together with other records.
If my crypto is stuck on a bankrupt exchange, can I record a loss?
Not automatically.
The tax treatment of inaccessible cryptocurrency depends on the facts and the tax rules applicable to the taxpayer. A bankruptcy claim, potential recovery, or later distribution can affect the analysis.
Do I need to reconcile previous years?
Often, yes.
If historical transactions affect the cost basis or balances of assets held during the current tax year, earlier years may need to be reviewed even if the immediate goal is to prepare a current-year tax return.
Should I use a crypto accountant for a failed exchange?
It can be useful when the account involves multiple years, large transaction volumes, missing records, multiple wallets, DeFi activity, or a bankruptcy claim.
A crypto accountant can help reconstruct and document the transaction history, while a qualified tax professional can address the applicable tax treatment.
Final Takeaway: Missing Exchange Data Does Not Mean the Tax History Is Lost
When a crypto exchange shuts down, becomes inaccessible, or enters bankruptcy, the normal API or CSV-based reconciliation process may no longer work.
But that does not mean the investor's tax history is impossible to reconstruct.
The key is to work systematically:
Identify the exchange status → collect every available record → reconstruct missing transactions → use blockchain and wallet data → match transfers → verify closing balances → investigate discrepancies → document manual adjustments → separately analyze tax treatment and later recoveries.
Most importantly, do not create transactions simply to make the software balance, and do not automatically classify inaccessible cryptocurrency as a tax loss.
A strong reconciliation is more than making the numbers match. It creates a transaction history that is supported by evidence, logically reconstructed, properly documented, and capable of being reviewed later.
Even when an exchange has disappeared, careful work can often recover enough information to establish a defensible crypto tax record.